Have you always paid at least your Minimum Amount Due on time, avoided late fees, yet when you check your credit health app, you discover your CIBIL score is still stagnant, or even getting worse? You’re not the only one. Millions of borrowers face this exact financial paradox because they focus only on payment timing and ignore the amount they borrow.
The reason for this stagnation is almost always the Credit Utilisation Ratio (CUR), since although payment history receives all the attention, CUR is the quietly influential factor, making up about 35% of the calculation of your CIBIL score. If you want to gain access to an elite credit tier, understanding this figure is no longer something you can afford to ignore.
How Does CIBIL Assess Your Spending?
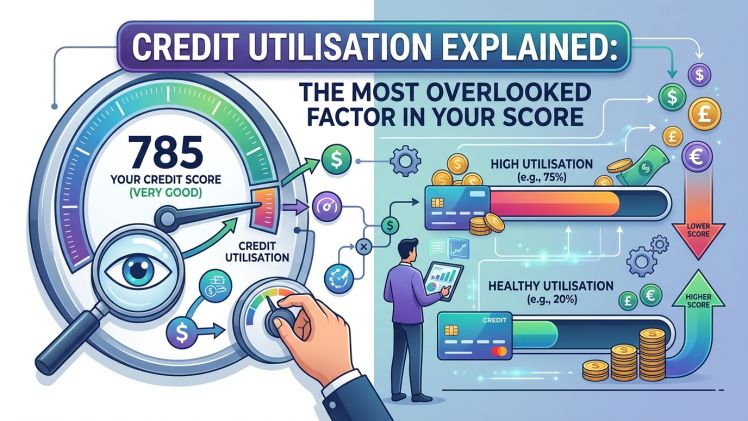
At the heart of your CIBIL score your Credit Utilisation Ratio is just a mathematical summary of how much credit you want to use; it shows the percentage of your total available credit limit that you are actually using at any one time.
For example, if you have two credit cards totalling a combined limit of ₹2,00,000 and the balance you currently owe on both of them is ₹1,00,000, your credit utilisation ratio will be 50%.
CIBIL keeps records of both overall and individual card utilisation. Even if all your other cards have no balance, using one card with a ₹50,000 limit to its full capacity will raise a red flag on your file. Because algorithmic credit scoring models see high utilisation as a sign of financial difficulty, a borrower who is nearly at their credit limit may appear to a lender as someone living beyond their means.
The 30% Rule: Being the Sweet Spot
The way to keep your CIBIL score healthy is to keep both your total and individual card usage below 30%; once you go above this figure, your credit profile changes from that of a safe borrower to one in the ‘risk zone ‘, and as a result, your score begins to decline. Yet if your aim is to achieve a top score of above 750 or 800, most people who score at the highest level generally keep their CUR below 10%.
Strategic Moves Which Can Help Lower Your CUR
Since CUR is highly dynamic, you can improve your credit rating quickly by managing it, and you can reduce your utilisation aggressively without cutting back on the spending you need by using these proven strategies.
Learn the mid-cycle strategy:
- Don’t wait until your monthly payment due date to pay your bill. Credit card companies report your balance to credit bureaus on the statement generation date, not the due date.
- If you pay a significant amount of your balance before the statement is generated, the bank will report a very low balance to CIBIL.
Use the RBI’s faster reporting:
- Under the RBI guidelines, financial institutions must report credit data to bureaus four times a month on a strict weekly calendar (the 9th, 16th, 23rd, and month-end).
- While mid-cycle changes to active balances are typically batch-processed during the month-end full file cycle, this faster reporting ensures that once your statement is generated or a loan account is cleared, the data is pushed to TransUnion CIBIL and updates your dashboard within a single week instead of taking an entire month.
About the Card Limit:
- Ask your current lenders to increase your credit limit since your income has grown. For example, if your credit limit rises from ₹2,00,000 to ₹4,00,000 while your monthly spending stays the same at ₹60,000, your CUR will immediately fall from a risky 30% to a perfect 15%.
Don’t close unused credit cards:
- It is a common mistake to close a credit card you no longer use, since doing so immediately reduces your total available credit and causes your overall usage ratio to jump sharply.
- You should keep those old accounts open, even if all you do is pay a small recurring utility bill.
Be on the lookout for the Add-On Card Trap:
- If you have given an add-on card to a spouse, child, or parent, remember that their spending counts against your primary credit limit.
- Keep a close eye on their spending since their heavy spending will have a direct adverse effect on your credit score.
Summary
The credit utilisation ratio is one of the simplest figures to improve since it has no memory at all; unlike the case with a late payment, which leaves a bad mark on your credit record for many years, a high CUR can be nearly immediately corrected by reducing your balances or by changing the way you spend.
Take this step now by logging into your financial dashboard, adding up your total credit limits, working out your current baseline percentage, and then begin making these small adjustments to see your CIBIL score rise. If you want an accurate figure, you can also check your CIBIL score on Bajaj Finance App’s in-app calculator, which offers you services so you can pay your bills easily through the app itself.